

A Guide to Business Insurance
Planning for Disaster
Do You Have Enough Business Insurance?
By Sharon Elaine Thompson
(Originally Published by MJSA June 2024)
Benjamin Franklin once famously quipped that “in this world nothing can be said to be certain, except death and taxes.” But for business owners, there’s another certainty that often lurks in the shadows: insurance. While many jewelers are diligent about basic coverage such as worker’s compensation and jeweler’s block policies, there are additional crucial areas of protection that are often overlooked. Expanding your insurance portfolio in these key areas can shield your business from unforeseen risks and ensure its long-term success.
Business Owner’s Insurance
Jewelry businesses may take a great sigh of relief once their jeweler’s block policy is in place because, first and foremost, they worry about their jewelry inventory. But there are other potential losses businesses face, and you need a business owner’s policy (BOP) to cover them.
“BOPs package together basic property liability and loss of income coverage and are generally best suited for small to medium-sized business,” says Carrie Volp, vice president of commercial lines operations at Jewelers Mutual in Neenah, Wisconsin. These are businesses with annual revenues under five million, adds Andrew Chipman, vice president of jeweler’s block for Berkley Asset Protection in New York City. (Larger businesses “can consider a Commercial Package Policy,” says Volp. “It serves the same purpose as a BOP but can allow for larger limits.”)
With additional endorsements, BOPs can cover internal theft, money and securities lost in a fire, appraisal equipment, accounts receivable, valuable papers and records, and an endless number of items you never think about until you have to replace them such as office and breakroom supplies.
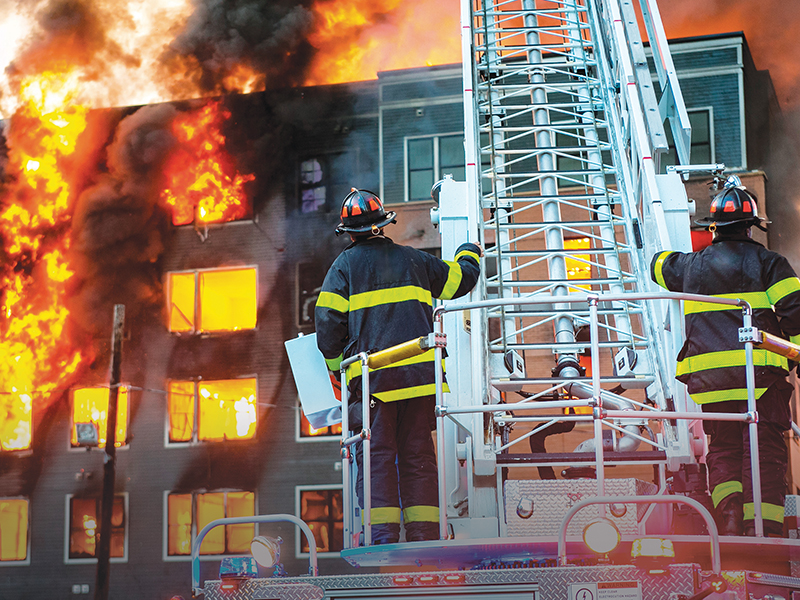
Skimping on a business owner’s insurance policy can cost you more
in the long run, as unprotected businesses that suffer a loss, such as from a fire, face a high likelihood of going out of business.
“Your cases, your carpet, any improvement that you’ve put in a space, even if you lease it, that can all be protected,” says Volp. “The loss of income that comes from that car going through the front of the location, the fire that maybe your neighbor started in one of their cooking fryers, the leaky salon chair from next door, can also be covered.”
Jewelers Mutual’s BOP also “gives full glass coverage with no deductible, which is very important to retail jewelers,” says Bill Genovese, president of the Child-Genovese Insurance Agency in Hingham, Massachusetts. This would include any breakage, from a skateboarder putting a board through your front window, to a thief smashing in and trashing cases.
However, although glass coverage is often covered in a BOP, there are usually deductibles. “A $1,000 deductible on a window may be more than the repair of the damaged glass,” he says. This is why it’s a good idea to “check with your insurance advisor to ensure you have appropriate coverage for glass, any lettering or safety glazing on the glass, as well as any glass break sensors or alarm features,” adds Volp.
BOPs also cover business interruption and loss of business income due to unforeseen disasters, including any continuing expenses you are legally obligated to pay. “So, your payroll, your rents, your utilities, all of that can be covered if you plan appropriately,” says Volp.
It’s important to note that loss of income and business interruption is not covered by a BOP unless the damage is to your building. If smoke or fire from the building next door damages your business, you would likely be covered, says Chipman. However, if an approaching hurricane knocks out power and you cannot conduct business without electricity, or there is a mandated shutdown due to an epidemic (as happened during the height of the COVID-19 pandemic) that is not covered because there was no actual damage to your location.
“There are times where you can buy what is called utility interruption to supplement your business income,” says Chipman. However, he adds, in places such as Florida, or any wind-prone state, “that coverage is extremely hard to obtain in today’s world.”
A BOP isn’t something you want to skimp on because it can mean the difference between failure and survival after a disaster. In fact, many businesses that suffer losses, such as that from a fire, are forced to close. According to the Federal Emergency Management Agency, 40 percent of small and mid-sized businesses never reopen after a natural disaster; an additional 25 percent of those that do reopen will fail within a year. The Small Business Administration says that 90 percent of businesses that suffer a fire go out of business within two years.
“Even a simple toilet overflow, which sounds silly, can be absolutely detrimental to businesses,” says Volp. This is why, some kind of business coverage insurance is “absolutely necessary,” she says.
General Liability Insurance
When you mention liability, the word “lawsuit” comes to mind. In a classic scenario, a customer is injured by slipping on a wet floor or tripping on torn carpet. With liability insurance, you would be covered if they sued.
“Generally, most BOP policies will cover that type of experience, under what we’ll call a base policy,” says Volp. “That will cover those incidents.” Depending on what has happened, you may be covered for some legal fees that result from legal action.
(If an employee is injured while working, they will be covered by a workman’s compensation policy, which, says Chipman, is required by most states. That policy is separate from a general liability policy.)
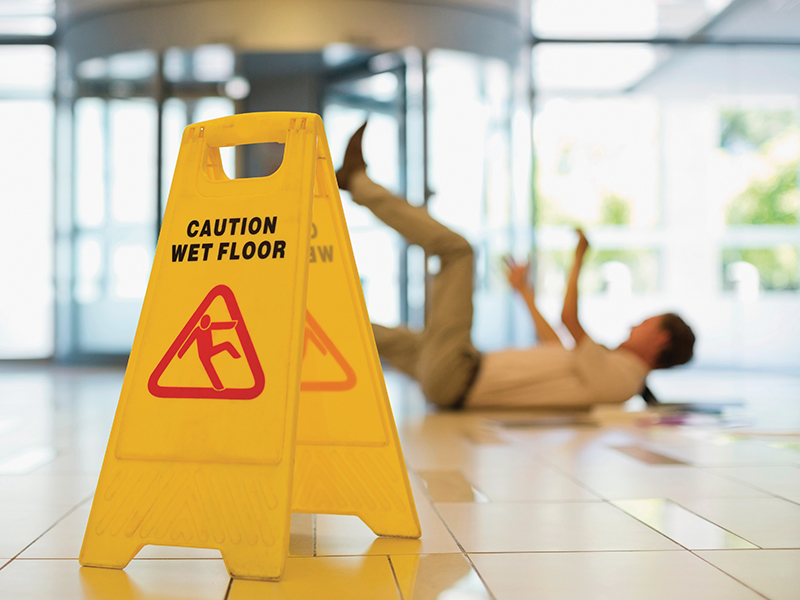
Although many business owner’s insurance policies will cover liability issues such as a customer injury, insurers recommend investing in an umbrella policy for additional protection.
If the event involves a catastrophic injury, such as one that entails hospitalization and surgery, “having an umbrella policy can even be more helpful,” she says. If that catastrophic loss would exhaust all of your insurance limits, the umbrella policy provides an additional coverage limit that will protect you. Though too few businesses take advantage of an umbrella policy, says Volp, “that is coverage that, I think, is very, very important to talk to your insurance advisor about,” especially in our litigious society. The premiums, she says, are very reasonable for that additional layer of protection. Without it, a plaintiff can go after your business, your assets, and even your personal portfolio. “You are really protecting things that you have worked a lifetime for,” says Volp.
A commercial liability policy also covers your legal liability in the event that a fire in your facility—due to faulty wiring in a display case or a mishandled torch—damages the building in which you lease space. If you own the building, it would cover damage to the neighboring businesses, if any.
However, Volp notes that “it is common for damage that results from workmanship to be excluded from the general liability coverage.” So, if you do repairs or custom work, you should have workmanship coverage, too, says Genovese. If your business is repairing a diamond ring, and the setter damages the stone, workmanship coverage can help protect you. It has various limits depending on the needs of a particular jeweler.
employment
Employment Practices Liability Insurance
Liability suits don’t always come from someone outside the business. In fact, being sued for wrongful termination or harassment is more likely than being sued by a third party.
“In today’s world, everybody, both employee and employer, obviously should be conducting themselves to the highest professional standards,” says Chipman. But that doesn’t always happen. As a result, an employee who feels like they’ve been harassed, unfairly targeted, or unfairly treated, whether physically or emotionally, may sue your business.
An employment practices liability policy (EPLI) would cover accusations, such as age, race, disability, or gender discrimination in hiring or dismissal; sexual harassment; unequal pay; defamation; and retaliatory discharge.
Insurers recommend businesses have an employment practices liability policy to protect against accusations such as age, race, disability, or gender discrimination in its hiring or dismissal practices.
Before you dismiss this kind of coverage, remember that no business is too small to be sued. Even businesses with one employee can be at risk. In 2023, the Equal Employment Opportunities Commission (EEOC) reported that employment practices liability litigation was up 50 percent; in 2018, they reported that more than 40 percent of employment practices suits were against businesses with fewer than 100 employees.
These suits can be costly. Settlements out of court average $75,000; jury awards can be more than $200,000. Although the EEOC finds that, on average, more than half of these suits (55.8 percent in 2000 to 62.9 percent in 2013) are found to have no reasonable cause, the business must still defend against them, to the average tune of $150,000. And employer defendants lose approximately 44 percent of the cases litigated. More than 60 percent of small businesses assume they are covered for this kind of risk, when they aren’t.
Volp says businesses should discuss their specific circumstances with their insurance agent, and make a decision based on the risk they’re comfortable taking on. If it’s you and your spouse and one other trusted employee who has been working with you forever, you may not need EPLI coverage. “But if you have employees that come and go seasonally, or if you have a large employment base,” she adds, “that’s maybe a risk you’re not comfortable taking on.”
It’s usually when your business gets larger, you have more than one location, or more than five employees, that you start looking into an EPLI policy, says Chipman. You’ll also want to consider where your business is located. In certain states, he says, there’s a greater “likelihood of unfavorable litigation toward business owners than in other states.” It’s there, he notes, that you’ll want to be extra diligent, “maybe going the extra mile to protect your assets that you’ve worked hard for.”
Remember that discrimination suits can come from customers as well, says Genovese. Even if it turns out that there is no basis for the suit, he says, you’ll still have to defend against the charge. “You really want your insurance company standing behind you, instead of [you standing by] yourself with an open checkbook,” he says. Your insurance company will have an attorney that specializes in this kind of suit and will be able to provide assistance across most of the country.
Natural Catastrophe Insurance
Over the last several years, climatic catastrophes, such as hurricanes, floods, sinkholes, and wildfires, have been prominent in headlines as have the images of the destruction they’ve wrought. Umbrella policies will not cover these kinds of disasters, says Volp, so you’ll want to be sure you have the property coverage you need to cover your building, your fixtures, and the things inside your leased or rented space.
Naturally, flood, wind, fire, or earthquake insurance will be more expensive in areas in which the situation is more likely to occur. But headlines have also been full of news of insurance companies leaving regions that have been hard hit by such catastrophes.
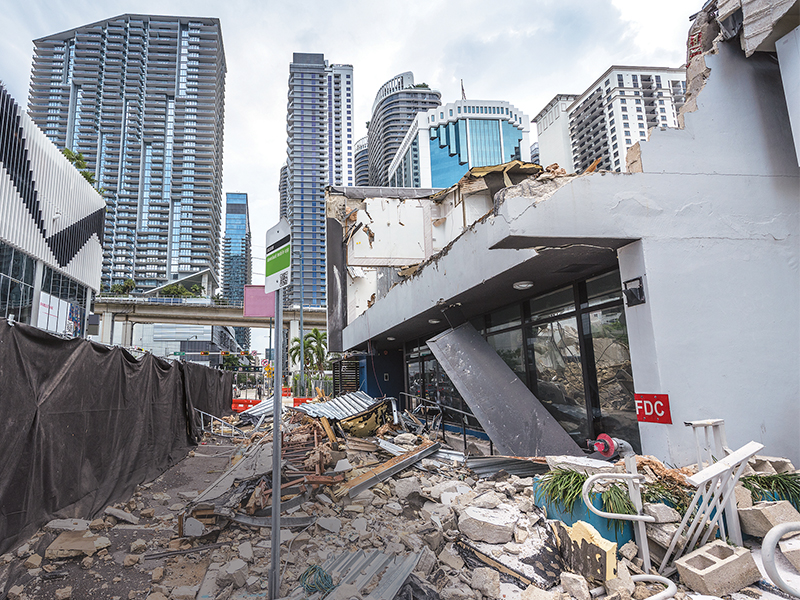
Businesses should consider natural catastrophe insurance because although natural disasters can be covered by a property insurance policy, there can be gaps depending on what caused the damage.
“The increase in natural disasters, the frequency of them, and also the severity of them is really changing the insurance landscape,” acknowledges Volp. So, how do you protect your business from either your policy being cancelled, because an insurer does not want to provide a specific type of coverage, or from paying high premiums that are the result of insurers having to raise rates to cover such disasters?
Your insurance agent or broker, says Volp, should know which carriers are thinking of pulling out of a market, a state, or even a region within a state. He or she should also be checking the market every year to ensure that you are with the right carrier. But it’s also up to you to be aware of the changes happening in your region. If your location might be at risk from wildfire, flood, sinkholes, or hurricanes, you’ll want to consider an appropriate increase in protection.
If you live in an area where insurance companies have paid a lot of large claims, says Chipman, think about the number of claims you submit. “Don’t submit a lot of small losses,” he says. “Save the insurance for things that are going to be catastrophic to your business.” Say, for example, your polishing motor burns out. Instead of submitting a claim for its replacement, spend $200 to $300 to replace it yourself. “I’m not saying that anybody isn’t owed what’s due to them under their policy,” he says, but the goal is to be a good partner.
It’s also important to do whatever you can to protect your business or prevent or mitigate a loss. Tack down rugs that could cause a fall. Mark stairs. Install water sensors wherever there might be a leak, such as by your water heater, toilet, or other plumbing fixtures. Have a code word if you think you’re being cased. Have good surveillance cameras and adequate physical protection of your facility, adding a man trap if necessary, or bollards in front of your store so no one can drive a car in.
Show that you are thinking ahead and taking the potential for catastrophic damage seriously, says Chipman. In wildfire-risk areas, invest in fire suppression systems. In areas of high flood risk, get as much of your equipment as possible off the ground. Make sure that you’re code compliant for wind storms. Whatever steps you’ve taken, be sure your insurer knows what you’ve done.
“All of those things are an investment,” says Volp. “They’re also a risk mitigation strategy. Big insurance companies love it if you do that on the front end versus not doing that at all.”
“We’re here to step in at times of loss,” adds Chipman. “But if you can avoid having the loss in the first place, it really saves it for when you really do need it.”
Take advantage of the disaster preparedness resources offered by most insurance companies, says Volp. What kinds of plans can you put into place to aid recovery from a disaster?
“If you lose power for a week because of ice storms, do you have a generator?” While you can’t prevent a damaging weather event, to some extent you can control how you will recover from it and how badly it will impact you,” says Volp. “Walking through all of that [with your carrier] well in advance [of a disaster] will really help on the claim side.”
Even after a disaster happens, says Chipman, it’s important to understand that your business will be working in partnership with the insurer. It’s not, he says, a matter of simply waiting until the building is repaired. You should be working with the insurance company to try to find some type of other temporary space where you can conduct your business, he says. You’ll still experience a loss, but the goal is to help get you “back up on your feet and running until the other place can be repaired,” he says.
How Much Insurance Is Enough?
There is no “one-size-fits-all” when it comes to determining how much insurance to have, says Chipman. However, “there is a tendency to obtain as little insurance as [the customer] feels they can afford,” he says. For example, a business can choose a reimbursement limit for the contents of their location—such as cash registers, showcases, flooring, wall textures—“anything that’s not jewelry. People typically will get as small a limit as they can for that, because they don’t want to pay a lot for the insurance. The issue with that is when something truly disastrous happens, the hundreds of dollars that you’re saving every year on your insurance policy will pale in comparison to trying to get your business back up on its feet, and you’ve only gotten a check from the insurance company for pennies on the dollar for what you truly had in the store, things that you’re going to need to replace now.”
There are two risks if you underinsure, says Chipman.
Although business owners may balk at the premiums to fully insure all aspects of their business, they risk the possibility of losing their livelihood should a catastrophic event affect the business.
The first is that unable to replace all that you need to, you go out of business. “That’s a real possibility,” he says. “The other possibility, though, is that people take on additional mountains of debt that they hadn’t anticipated taking on because that is their livelihood. Maybe you’re still in business, but now your retirement window, or other goals, have now been suspended by X number of years for something that wasn’t accounted for.”
So, insure your business properly. Go through your facility and try to see, with fresh eyes, all that would have to be replaced in the event of a fire or other disaster: furniture, cases, plants, art, wall mirrors, computers, electronic devices, breakroom furniture, refrigerator, books, stationery, tags, boxes, job envelopes, shop equipment, and findings. Check your rental agreement to find out whether you or your landlord is responsible for glass breakage or equipment breakdown losses.
Talk to your agent about commercial liability as well as employment practices liability. Once you have all the figures, compare the cost of an annual premium against the risk of a loss or suit. When you’re planning for disaster—and that’s what buying insurance comes down to—you want to broaden the coverage as much as possible.
Always deal with an agent who specializes in the particular kind of insurance you’re buying. They’ll know the latest laws and have access to various companies offering a range of services. Don’t be afraid to examine multiple programs to find the one that best suits your needs.
Be sure the agent is jewelry industry savvy, adds Genovese. More than once, he says, he’s seen policies written by non-specialists that the policy holder is convinced covers their jewelry. “I’ll look through the whole policy, and I’ll find an endorsement on a jeweler’s business owner policy that has a jewelry limitation of $5,000.”
“Don’t let price be the main driving factor as to who you insure with,” says Chipman, because “at the end of the day, if you’re not insured for the things that you haven’t thought of, those are things that will have a real impact on you and your business.
“After a total disaster, or a total catastrophic event,” he adds, “I’ve never heard anybody say, ‘I wish I wouldn’t have spent that money on insurance.’”